Photo: He Qijie/VGC, Getty Images
The Macro-Context of Global Logistics in 2026
For nearly three years, the architecture of global maritime trade has undergone its most significant structural shock since the containerisation revolution. Security risks in the Red Sea and the Bab el-Mandeb Strait forced Asia–Europe container services, bulk carriers and tankers to abandon the Suez Canal corridor — a transit artery handling roughly 12% of global trade — in favour of the historic detour around the Cape of Good Hope.
As the industry enters the final stretch of 2026, a new phase is underway. Major carrier networks, including the Gemini Cooperation between Maersk and Hapag-Lloyd, MSC and COSCO, have begun a calculated and phased return to the Suez route, highlighted by the transfer of major loops back through the Red Sea. Yet this shift remains far from a complete return.
Sea-Intelligence data places overall Suez and Red Sea routing normalisation at approximately 27%, leaving the majority of head-haul traffic firmly anchored to the Southern African maritime pathway.
This analysis examines the economic and security implications of this transitional era, including global supply-chain adjustments, the impact on Southern Africa, energy flows from Arab exporters and Indian refineries and the evolving risk architecture surrounding the world’s principal maritime chokepoints.
1. Global Container Shipping Economics and Fleet Dynamics
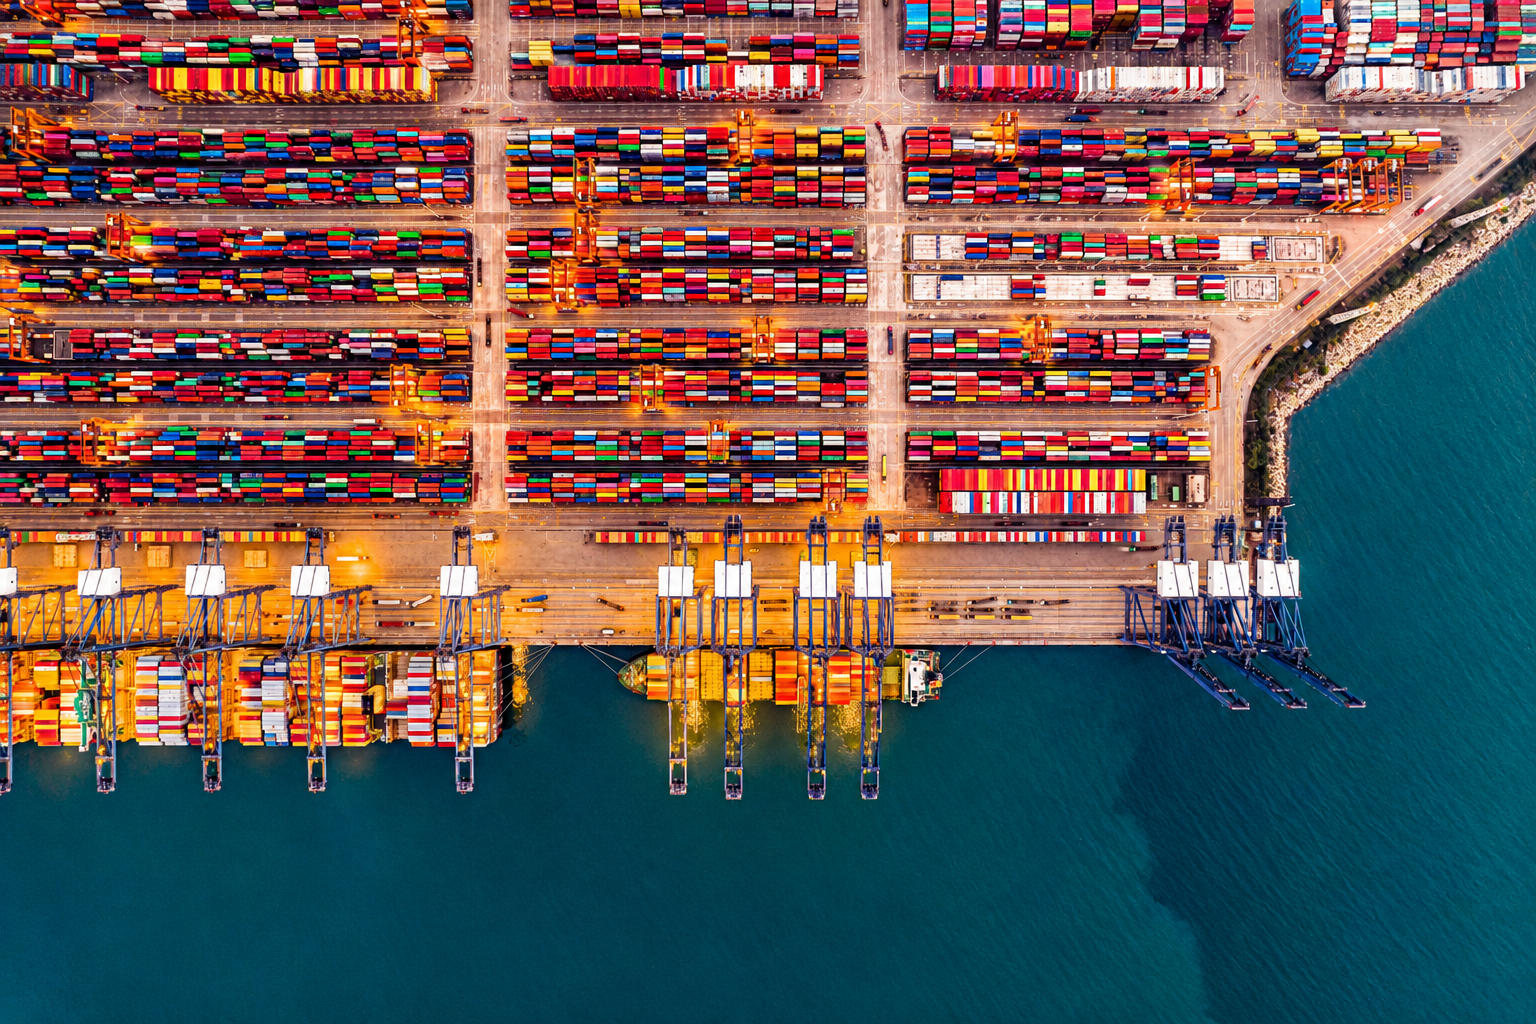
The forced diversion around the Cape of Good Hope added between 3,000 and 4,000 nautical miles to individual voyages, extending transit times by approximately 10 to 14 days and often longer depending on destination and service rotation.
The Capacity Sponge and Market Absorption
From a macroeconomic perspective, the Cape detour functioned as a massive capacity sponge. By lengthening voyage loops, the industry absorbed roughly 5% to 7% of global container fleet capacity, effectively reducing fears of severe overcapacity that might otherwise have driven freight rates sharply down following post-pandemic normalisation.
With September 2026 normalisation metrics showing an approximately 27% return to Suez, an asymmetrical dynamic has emerged.
- Asymmetrical directionality: The return is heavily skewed towards back-haul routes from Europe to Asia. Mediterranean-to-Asia services have reached approximately 57% Red Sea routing share as carriers seek to reposition empty containers efficiently towards Asian manufacturing hubs.
- Head-haul hesitation: Asia-to-Europe capacity remains considerably more cautious, hovering between approximately 13% and 25% normalisation as carriers continue to reassess security protocols, hull insurance premiums and schedule reliability.
Rate Pressures and Market Corrections
The partial reopening of the Suez corridor has introduced downward pressure on spot freight rates, particularly on Asia–Mediterranean lanes, which experienced double-digit corrections during September 2026.
However, shippers cannot assume a return to pre-crisis pricing. Elevated bunker-fuel costs resulting from prolonged voyages and persistent war-risk insurance endorsements, averaging around 0.5% to 1.0% of a vessel’s hull and machinery value for Red Sea transits, continue to keep operating costs high.
2. Energy Logistics: Arab Crude, Indian Refineries and Tanker Flows
The maritime realignment extends well beyond containerised manufactured goods and is directly reshaping global energy corridors involving Middle Eastern crude exporters and major refining centres such as India.
Energy Logistics Pathways and Routing Structure
Crude oil and liquefied natural gas originate from Persian Gulf exporting states and transit outward through the Strait of Hormuz into the Arabian Sea and Indian Ocean.
A significant proportion of these energy flows moves towards Indian refineries, where crude feedstocks are processed before refined petroleum products are exported westwards.
From the Indian Ocean, energy carriers increasingly face two distinct routing options:
- Route A – Higher risk, lower tonne-miles: Transit through the Bab el-Mandeb Strait, Red Sea and Suez Canal towards Europe.
- Route B – Lower regional security exposure, higher tonne-miles: Diversion around the Cape of Good Hope and northwards through the Atlantic towards Western markets.
The Hormuz–Suez Energy Axis
A significant volume of global crude oil and liquefied natural gas originates in Arab exporting states such as Saudi Arabia and the United Arab Emirates and transits through the Strait of Hormuz.
Under normal operating conditions, these cargoes can continue past Bab el-Mandeb and through the Suez Canal towards Mediterranean and Northern European markets.
Structural instability in the Red Sea has forced tanker operators and product carriers to calculate a difficult risk-reward balance.
- The surcharge burden: Red Sea transit exposes tankers to heightened security risks and elevated war-risk insurance premiums, increasing the delivered cost of energy cargoes.
- Tonne-mile expansion: Diverting crude and refined product carriers around the Cape of Good Hope significantly increases tonne-mile demand, locking up tanker capacity for longer periods and affecting vessel availability and global refining margins.
The Strategic Role of Indian Refineries
India has consolidated its position as a central processing hub within global energy markets, importing crude feedstocks from the Middle East and Russia while exporting high-value refined petroleum products westwards.
Indian refineries must continuously balance the increased cost of Cape routing against the speed-to-market advantages offered by Suez.
As selected services return to the Suez route, Indian exports destined for Mediterranean and European ports can benefit from shorter transit times. Nevertheless, energy logistics planners continue to maintain diversified chartering and routing strategies to reduce exposure to any renewed security disruption.
3. The Geopolitical and Economic Impact on Southern Africa
For countries situated below the equator, including South Africa, Namibia, Mozambique and Mauritius, the prolonged diversion away from Suez transformed regional waters into one of the world’s busiest and most strategically important maritime trade corridors.
The Double-Edged Sword of Port Congestion
The large-scale diversion of container ships, bulk carriers and tankers around the Cape of Good Hope created both substantial economic opportunities and significant operational pressures.
- Bunkering and maritime services boom: Regional ports experienced increased demand for marine fuel, provisions, freshwater replenishment, crew changes and ship-repair services. This generated additional foreign-exchange earnings and stimulated local maritime economies.
- Infrastructure bottlenecks: Ports designed around much lower baseline traffic volumes, particularly Durban and Cape Town, faced increased yard densities, equipment shortages and longer vessel turnaround times.
- Structural weaknesses: The surge in traffic exposed longstanding underinvestment, bureaucratic delays and maintenance backlogs affecting port infrastructure, rail systems and landside logistics.
Structural Adaptation and Long-Term Modernisation
With the Cape route continuing to handle a dominant share of diverted global traffic, regional authorities and logistics operators have accelerated institutional reforms and infrastructure investment.
Public-private partnerships involving Transnet and international terminal operators aim to inject capital and improve operational efficiency at strategic South African ports.
At the same time, secondary ports such as Ngqura, Port Elizabeth and Walvis Bay have increasingly acted as relief hubs, absorbing overflow traffic and reducing pressure on more congested terminals.
4. The Interconnected Chokepoint Architecture
Modern maritime trade can no longer be understood simply as a collection of independent shipping lanes. It increasingly operates as an interconnected system of strategic chokepoints in which disruption at one location can immediately affect pricing, vessel availability, insurance costs and port congestion elsewhere.
Strait of Hormuz
- Primary geographic link: Connects the Persian Gulf with the Indian Ocean.
- Current status and vulnerability: Remains highly sensitive to regional geopolitical developments and potential disruptions.
- Logistics impact: Any restriction on flows can affect crude oil and LNG exports and rapidly influence global energy and bunker-fuel prices.
Strait of Malacca
- Primary geographic link: Connects the Indian Ocean with the South China Sea.
- Current status and vulnerability: Maintains extremely high traffic density and carries a substantial proportion of global maritime trade and East Asian energy imports.
- Logistics impact: Extended Asia–Europe voyage cycles can increase congestion and capacity pressures across the route.
Bab el-Mandeb and the Red Sea
- Primary geographic link: Connects the Indian Ocean and Gulf of Aden with the Red Sea and Suez Canal.
- Current status and vulnerability: Undergoing a phased and partial recovery, with overall routing normalisation estimated at approximately 27%.
- Logistics impact: Security conditions determine whether carriers use the shorter Suez route or divert thousands of additional nautical miles around Southern Africa.
The Horn of Africa
- Primary geographic link: Encompasses the Somali Basin and Gulf of Aden.
- Current status and vulnerability: Continues to face security challenges requiring sustained naval monitoring and patrol activity.
- Logistics impact: Security concerns increase insurance premiums and impose stricter routing requirements on vessels approaching the Red Sea.
Cape of Good Hope
- Primary geographic link: Connects the Atlantic and Indian Oceans around Southern Africa.
- Current status and vulnerability: Has become the principal alternative corridor for much of the Asia–Europe traffic diverted from the Red Sea.
- Logistics impact: Adds approximately 10 to 14 days or more to many voyages, absorbs significant global fleet capacity and creates additional economic activity for Southern African maritime economies.
This interconnected architecture means that developments in Hormuz can rapidly alter global bunker-fuel pricing, while instability around Bab el-Mandeb can influence vessel scheduling and port productivity as far away as Durban, Singapore or Rotterdam.
5. Strategic Outlook and Future Industry Implications
As the maritime industry navigates the remainder of 2026 and prepares for the years ahead, several structural changes appear likely to remain embedded in global trade.
The End of Just-in-Time Complacency
Supply-chain planners can no longer assume that the shortest and cheapest maritime route will always remain available.
The experience of a regional security crisis adding two weeks or more to transit times has strengthened the case for multi-sourcing, regional near-shoring and larger safety-stock buffers.
Supply-chain resilience is increasingly being treated as a strategic requirement rather than an additional cost.
Hybrid Routing as the New Normal
Even as carriers including Maersk, Hapag-Lloyd, MSC and COSCO gradually return selected services to the Suez Canal, maritime networks are increasingly being designed around redundancy.
The Cape of Good Hope is no longer viewed purely as an emergency diversion route. It has become a viable long-term alternative capable of reducing dependence on a single chokepoint and providing carriers with greater flexibility when security conditions deteriorate.
The emerging system is therefore not necessarily a return to the pre-crisis Suez model, but the development of a dual-route structure in which traffic can shift between Suez and the Cape according to security, insurance, fuel costs and operational requirements.
The Strategic Rise of African Maritime Governance
African coastal states have demonstrated their importance to the continuity of global commerce during periods of disruption.
For Southern African countries, the central challenge will be converting temporary traffic increases into sustainable economic and strategic gains.
This requires continued investment in port automation, digital customs systems, rail infrastructure, ship-repair capacity, bunkering services and maritime security.
If these investments are sustained, the Cape route could retain considerably greater strategic importance even if Red Sea traffic continues to recover.
Conclusion
The gradual return of shipping to the Suez Canal should not be interpreted as a simple restoration of the maritime system that existed before the Red Sea crisis.
Instead, the global shipping industry is entering a period of strategic recalibration. Carriers, energy companies and governments are increasingly operating within a dual-route environment in which the Suez Canal and Cape of Good Hope function as complementary rather than mutually exclusive corridors.
Security conditions around Hormuz, Bab el-Mandeb and the Horn of Africa now interact directly with freight rates, energy markets, tanker availability and port activity thousands of kilometres away.
The central lesson of the past three years is therefore broader than the question of whether vessels return to Suez. Global maritime trade has become more geographically diversified, more security-conscious and increasingly dependent on redundancy.
The Suez–Cape dual-route era may consequently prove not to be a temporary response to crisis, but one of the defining structural changes in twenty-first-century global logistics.
Author: Mauritius-based Bruneau Laurette is Director of DRCS Africa HQ and an elite defence and security consultant with over 25 years of experience in high-risk environments, maritime anti-piracy and port security. He has advised the governments of Mauritius, Seychelles and Tanzania, established specialist tactical units and trained law enforcement and correctional officers.